For those of you keeping score at home, VoxEU has a handy chronology of the financial crisis.
Showing posts with label financial crisis. Show all posts
Showing posts with label financial crisis. Show all posts
Sunday, May 3, 2009


Tuesday, April 14, 2009
About that money under the mattress...
Via Bloomberg: "The London interbank offered rate for three-month dollar loans is dropping at the fastest pace since January." This is one positive indicator that credit is starting to flow again in financial markets. At the same time, Goldman Sachs announced that it would sell stock to facilitate repayment of $10 billion in TARP funds to the US government, ostensibly to avoid some of the more prickly (compensation-related) strings attached to the government funds. Goldman Sachs also posted a $1.66 billion profit in Q1.
Good news is welcome news, but two happy stories do not make a turnaround. The Goldman Sachs development may even be counterproductive if other banks rush to pay back their own TARP funds so as not to appear weak, in what would amount to a very public stress test. There is also a danger that Congress, already suffering from bailout fatigue, will become even less inclined to authorize more financial stabilization spending. That's worth keeping in mind, because not everyone is as optimistic as this.
Good news is welcome news, but two happy stories do not make a turnaround. The Goldman Sachs development may even be counterproductive if other banks rush to pay back their own TARP funds so as not to appear weak, in what would amount to a very public stress test. There is also a danger that Congress, already suffering from bailout fatigue, will become even less inclined to authorize more financial stabilization spending. That's worth keeping in mind, because not everyone is as optimistic as this.
Wednesday, April 8, 2009
A false dawn
April is the cruelest month - if you're an economist. Seriously, the dismal science has outdone itself in the past week. Here are some graphs charting the collapse in trade flows. (Bonus: here are some related statistics and graphs tracking the slowdown of bilateral US-UK trade). Here are some measuring the even faster disintegration of capital flows. Here are some which show that by every indicator, the global economy is tracking or doing worse than during the Great Depression. And here is the impossible (to paraphrase Felix Salmon) list of things we would need to do to avoid another Black Swan like this occuring in the future.
I am most troubled by the argument that current aggressive policy responses may eventually end the recession without addressing the fundamental problems which caused it in the first place. Green shoots? Try cold snap.
I am most troubled by the argument that current aggressive policy responses may eventually end the recession without addressing the fundamental problems which caused it in the first place. Green shoots? Try cold snap.
Tuesday, April 7, 2009
Fund-amentals
 Plenty have highlighted the promises to the IMF as one of the greater success of the G20 Summit. Free Exchange doesn't agree:
In the quest for a big headline number to throw at the world and the press, and in an attempt to equate this to the missing globally coordinated fiscal stimulus, there's been a fair amount of hand-waving. Of the money that the IMF is supposedly getting, the only clear new commitment is a relatively small $40 billion from China.
True, the new commitments aren't as stellar as the media is reporting. But, the big change is not the new money; it's the Flexible Credit Line. To be fair, the author correctly notes that countries aren't exactly lining up for these IMF handouts. But if Mexico has a decent time with the revamped IMF system, you better believe a few more governments will be putting in a call to Mr. Strauss-Kahn.
Besides, the amount of money isn't that important: it's the fact that after years spent resisting change and asserting their right to essentially dictate monetary policies to countries (ahem, Thailand), the IMF is loosening its grip, albeit slowly. Countries still must have "sound monetary policies" to qualify for these new loans. But the definition of "sound" hasn't been spelled out and more importantly, the loans don't come with IMF staff. With nationalist rhetoric rising in the wake of the financial crisis, taking IMF money is going to be a much easier political sell if it doesn't come with resident Fund officials. The US and Europe may still have de facto veto power within the Bank group, but that's something most people won't know when they head to the ballot box.
(Photo from Kyrion)
A chocolaty financial crisis metaphor
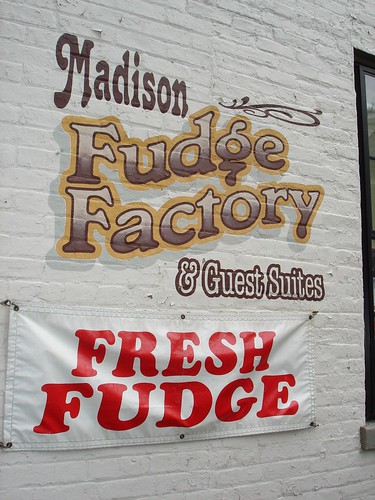 Among all of the recent metaphors used to describe the financial crisis, this one takes the cake (or fudge).
Special thanks to The Browser and The Financial Times.
(Photo from merfam's photostream)
Monday, March 30, 2009
Gallows humor
President Obama has had a rough few months. As the global economy continues its slide, what the crisis means for global trade and financial regulation will dominate discussions in London on Thursday. Rightfully so. After the economy, North Korea's impending missile launch and Afghanistan's gradual decline into disarray dominate any foreign policy discussions. With so much on his plate, not to mention health care reforms and an understaffed Administration, Iraq has fallen by the wayside. The President has admitted as much.
But lest we forget how perilous the gains we've made in Iraq are, Tom Ricks is happy to remind us:
The Maliki government is putting the screws to the Awakening movement (for those who just arrived, that's a mainly Sunni group of about 100,000 people, many of them former insurgents, who in late 2006 and 2007 arrived at ceasefires with the U.S. military presence in Iraq). The American plan was to integrate 20,000 members...into Iraqi security forces, and help the rest find other work...But the Shiite-dominated Baghdad government never really like the idea. Indeed, the first deals were cut by U.S. officials behind the back of the Iraqi government...I think Maliki's gambit is to crack down on the Sunnis while American forces are still available in sufficient numbers to back him up. This is turning into a test of strength, Sunni vs. Shiite.
Sound familiar?
The President may be better served to focus on actually shoring up our international standing, rather than just paying lip service to the notion while using our current crisis environment to push big government, domestic programs that most independent voters hoped he would avoid.
Tuesday, March 24, 2009
A visual explanation of Geithner's two-pronged plan
The FT has a handy graphic explaining how Secretary Geithner's plan will actually work if you're a little bit confused.
Sunday, March 15, 2009
More financial crisis visualizations
27 visualizations and infographics to understand the financial crisis.
Monday, March 9, 2009
The food crisis never ended
 Christopher Delgado, an agricultural policy advisor at the World Bank, recently said of the global food crisis, "The food crisis has not gone away...In fact, it is coming back."
Combing through the media, it would be easy to assume that the food crisis had long ago subsided as demand for imports, commodity prices and economic growth declined. However, risks to food security and the possibility of famine are still very high in many countries. While food commodity prices have fallen from their record highs in 2007, the US Department of Agriculture forecasts that they will remain above historical levels in 2009. The combination of rising food prices, economic contraction, export/price controls and tight trade credit exposes many vulnerable countries, particularly LDCs, to serious risks of famine, poor crop yields and higher prices coinciding with falling income. This doesn't even begin to include the impact on food production by drought, land degradation and other environmental conditions; the UN recently warned that global food production may fall 25% by 2050.
Given the still prevalent risks, it is disconcerting that less is being done to combat the problems directly. Further, certain policy responses to the financial and economic crises, such as looser monetary policy in the developed world, or expropriation in countries like Venezuela, risk stoking the rising food commodity prices. Which brings me to the real danger on the horizon (beyond, of course, the human cost): that the financial, economic and food crises will reinforce each other in a vicious cycle. A food crisis is a likely second-round affect of the financial and economic crises, which in itself breeds political and economic instability, undermining the recovery process and further destabilizing the global economy.
Policy responses to the financial and economic crises are understandably driven by the need for immediate action; to stop the bleeding, so to speak. But what if the very policies necessary to bring us out of this downward spiral only reinforce it in the medium-term?
(photo from snake.eyes' photostream)
Friday, March 6, 2009
Should I stay or should I go?
It's a testament to how bad things have gotten when people are already thinking about whether Treasury Secretary Tim Geithner should step down.
Kind of like Martin Wolf wondering out loud whether Obama's presidency has already failed. And that was a month ago! Think of everything that's happened since then.
Er, actually, maybe it's best not to think about...
Kind of like Martin Wolf wondering out loud whether Obama's presidency has already failed. And that was a month ago! Think of everything that's happened since then.
Er, actually, maybe it's best not to think about...
Sunday, March 1, 2009
The Crisis of Credit Visualized
If you're looking for a fun and easy-to-understand explanation of the causes of the credit crisis, check out this cool video produced by Jonathan Jarvis:
Subscribe to:
Posts (Atom)


